Acima Leasing

Screenshots
Details
- Rating
- 2.24K reviews
- Version
- 5.3
- Developer
- Acima
Analysis by Norviv
I spent time with Acima Leasing as a finance app, and my first impression is that it is aimed at a very specific moment: you want an item now, but a standard credit card or traditional financing route is not a comfortable fit. The app is free to install, developed by Acima, and presents itself as a no-credit alternative to conventional financing. That wording matters, because this is not a general budgeting app, a banking replacement, or a tool for building a complete household financial plan.
Its usefulness depends less on how many screens it has and more on whether its leasing option fits your situation. I found the app most relevant when I treated it as a way to explore an alternative payment path rather than as a promise of cheaper borrowing. That distinction is the key to using it responsibly.
What Acima Leasing actually offers
Acima Leasing belongs in the personal finance category, but its focus is narrower than apps that track spending, manage bank accounts, or compare investments. The central idea is to help users consider leasing when traditional financing may not be available or desirable. In practical terms, that makes it a decision-support tool for a purchase, not a complete financial command center.
The app has been available since June 4, 2021, and the current version is 5.3. It supports devices running Android 7.0 or later, while its content rating is Everyone. Those details make it accessible to a broad range of Android users, including people using older phones, although compatibility alone does not determine whether the financial arrangement is suitable.
Acima has built a noticeable audience: the app has passed one million installs, with an average rating of 3.8 from around 4,600 ratings and roughly 2,200 written reviews. I read that combination as a sign of a useful but not universally smooth experience. There is enough adoption to make the app worth examining, yet the rating also suggests that expectations and real-world outcomes can differ.
How the free app should be understood
There is no charge to download Acima Leasing. That is the clearest verified cost attached to the app itself, and it is an important advantage for someone who wants to investigate the option before committing to anything. You are not paying an app-store fee simply to open the service.
That free access should not be confused with a free purchase. The app is connected to a leasing decision, so the financial cost belongs to the agreement and the item being obtained, not to the download. I would approach every offer as a separate financial commitment and read its terms carefully before accepting it. The app’s price and the price of the underlying arrangement are two different questions.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is also why I would avoid judging the service only by the word “free.” Free access is valuable when it lets you investigate an option without an upfront app cost. It does not, by itself, prove that leasing is less expensive than paying cash, using a conventional loan, or choosing a credit card with terms you fully understand.
The workflow I would use before agreeing
My preferred workflow is deliberately slow. First, I would identify the exact item I need and the amount I can realistically afford over time. Next, I would use the app to explore whether the leasing route is available for that situation. Only after that would I compare the full obligation with the cash price and with a conventional financing offer.
A useful habit is to write down the total amount you expect to pay, the timing of payments, and any conditions attached to early purchase or completion. Do this outside the app if necessary. A phone screen can make a recurring commitment feel smaller than it is, especially when attention is drawn to the immediate payment rather than the overall cost.
I would also keep screenshots or personal notes of the figures and terms shown during the process. That is not a criticism of Acima specifically; it is a sensible practice for any financial product. It gives you something to review calmly later instead of relying on memory after a quick checkout conversation.
Where the value comes from
I find the value of Acima Leasing less in making a purchase effortless than in giving someone another route to examine when ordinary credit is out of reach. The useful move is to treat that route as a comparison point: set a firm spending ceiling first, then check whether the item and its full obligation still fit. That framing helps clarify the tradeoffs that deserve attention.
An alternative for people shut out of ordinary credit
The strongest value is accessibility. Someone with limited credit history or a recent financial setback may find a traditional loan difficult to obtain. Acima Leasing is designed around the idea of a no-credit alternative, so it may open a path that a bank, credit-card issuer, or standard retailer financing plan does not.
That can matter in an everyday emergency. Imagine a household appliance stops working shortly before payday. Replacing it may be necessary rather than optional, but the household may not have enough cash immediately and may not qualify for a conventional credit product. In that situation, the app can be useful as a starting point for exploring whether leasing is possible, while the user compares the long-term obligation with other ways to solve the problem.
The important nuance is that access is not the same as affordability. A person may be accepted for an arrangement and still find the complete cost uncomfortable. I see the app’s value in giving users another route to investigate, not in removing the need for careful arithmetic.
It keeps the decision close to the purchase
Unlike a general finance tracker, Acima Leasing is relevant at the moment a purchase is being considered. That focus can be helpful because it keeps the question concrete: what do I need, what can I pay, and what does this alternative mean for my budget?
For a user who does not want to open several unrelated finance apps, this narrow purpose is a strength. You can think about the financing route alongside the item instead of treating the purchase and the payment method as completely separate decisions. That makes it easier to notice when a necessary purchase is becoming an impulse purchase dressed up as a manageable payment.
My practical tip is to decide on a maximum total commitment before using the app. Set that limit based on your monthly budget, not on the amount the app or retailer makes feel comfortable. This simple step protects the tool’s convenience from turning into pressure.
Useful for comparison, not just approval
The most valuable way to use the app is as one option in a comparison. Traditional financing may offer a clearer total cost, a different repayment structure, or a better fit for someone with strong credit. Paying cash may be simpler when the purchase can wait. A credit card may be preferable for a user who can pay the balance in full and understands the card’s terms.
Acima Leasing becomes more useful when it helps you ask better questions: Is the purchase urgent? Would waiting avoid the commitment? What is the total amount under each route? Does the item remain affordable if another bill rises next month? Those questions add more value than simply finding a way to complete the transaction today.
Accessibility and basic discoverability
The Everyone content rating and Android 7.0 minimum make the app approachable from a device-compatibility standpoint. Its free availability also lowers the barrier to checking whether the service is relevant. For a person who has been told that ordinary credit is not an option, that low-friction first step can be meaningful.
Still, accessibility should not be mistaken for simplicity. Financial language can be easy to skim and hard to evaluate. I would take time to distinguish the item’s price, the payment schedule, and the total obligation. If any part is unclear, I would pause rather than treating the app’s availability as a reason to proceed.
Tradeoffs that deserve attention
I would be especially careful not to let a manageable-looking payment obscure the full commitment or crowd out essential bills. Before proceeding, I’d compare the lease with waiting, buying a less expensive item, paying cash, and any conventional offer available to me. Those checks make it easier to see when access is genuinely helpful—and when a different option is safer.
The total cost matters more than the first payment
The central drawback is the risk of focusing on short-term access while overlooking long-term value. A smaller initial payment can make an item seem affordable even when the complete arrangement costs more than another option. This is the tradeoff at the heart of any lease-to-own or alternative financing decision.
I would never compare offers using only the recurring payment. Put the cash price, the conventional financing total, and the leasing total next to one another. If you cannot identify the complete amount you may pay, you do not yet have enough information to make a confident choice.
This is especially important for nonessential purchases. A necessary replacement may justify considering more options, but furniture upgrades, electronics, and convenience purchases deserve a higher threshold. If the item can wait, saving first may be financially cleaner than accepting a commitment simply because the app makes immediate access possible.
Approval does not solve a weak budget
Another limitation is psychological. When a service offers an alternative to traditional credit, approval can feel like a solution in itself. It is not. The payments still compete with rent, utilities, food, transport, and unexpected expenses.
Before using the app, I would test the proposed payment against a bad month rather than a perfect month. If a minor repair or reduced work schedule would make the commitment impossible, the safer decision may be to delay the purchase, choose a less expensive item, or look for assistance that does not create another recurring obligation.
This is one area where a budgeting app or a simple spreadsheet may be a better companion than Acima Leasing. The leasing app can help with the purchase route, but it is not a substitute for seeing the rest of your finances in one place.
It is not the best tool for every borrower
Users with strong credit should compare conventional offers before assuming that a no-credit alternative is the best deal. A bank loan, retailer financing plan, or credit card may provide a lower overall cost or terms that are easier to understand. The right comparison depends on the actual offer, not on the category label.
Likewise, users who already have enough savings may prefer to pay cash and avoid a new obligation. The app can still be useful for checking an alternative, but the convenience of spreading payments should be weighed against the simplicity of owning the item without a financing commitment.
I would also skip the app for casual browsing if I already knew I was vulnerable to impulse spending. A tool that makes access easier can be unhelpful when the real goal should be waiting. In that case, a wish list, savings target, or spending freeze would serve me better.
Read every screen as a financial document
One non-obvious lesson from using a focused finance app is that the interface can encourage speed. The process may feel like a normal mobile checkout, but the consequences are closer to signing a financial agreement. I would treat every summary screen as something to review line by line, especially the payment timing, total obligation, and conditions that affect completion.
Do not rely on a verbal explanation alone. If a retailer or another person helps you use the service, ask to see the figures in writing and take time to consider them. A free app makes exploration easy, but it should not make commitment automatic.
Who will get the most value
The strongest fit, in my view, is someone facing a necessary purchase who has limited cash available, cannot comfortably use traditional credit, and can still evaluate the complete commitment calmly. A broken essential appliance is a more convincing reason to explore the app than an upgrade that can wait. With that distinction in mind, it becomes easier to decide who will get the most value.
A good fit for urgent, necessary purchases
Acima Leasing is most promising for someone facing a necessary purchase, lacking a comfortable cash reserve, and unable or unwilling to use traditional credit. The person should be prepared to compare the complete cost and should have a realistic plan for every payment.
The broken-appliance example is a reasonable fit because the need is immediate and practical. Even then, I would compare repair, a cheaper replacement, help from family, a community resource, and conventional financing before accepting a lease. The app is valuable when it expands the list of options, not when it narrows the decision to “approved or not approved.”
A possible fit for limited credit history
People who are new to credit or rebuilding after financial trouble may find the app relevant because its purpose is not tied to ordinary credit approval in the same way. That can provide a route to investigate when a standard application is discouraging.
However, I would not use it as a shortcut to repair my broader financial situation. If the goal is to improve credit, learn budgeting, or reduce debt, a nonprofit counselor, a dedicated budgeting tool, or direct work on existing obligations may be more appropriate. The app addresses access to a purchase; it does not replace a longer-term financial plan.
Who should choose another option
I would point a user toward another solution when the purchase is optional, the payment would consume most of the available monthly margin, or the user cannot clearly explain the total amount owed. I would also recommend comparison shopping for anyone who qualifies for a conventional offer with transparent, affordable terms.
Someone looking for investment tools, bill reminders, bank-account aggregation, credit monitoring, or expense categorization should not expect Acima Leasing to serve those purposes. Its identity is much more specific. Choosing it because it is in the finance category would be like choosing a repair tool when you actually need a household inventory.
Parents and younger users should also remember that an Everyone rating describes general content suitability, not financial independence. A user can safely view the app and still need an adult or trusted adviser to understand the commitment involved. Age suitability and financial readiness are separate issues.
My buy-or-skip verdict
I recommend trying Acima Leasing when you have a concrete need, traditional financing is not a workable route, and you are willing to compare the full obligation before accepting anything. The app is free to download, has broad Android compatibility, and offers a focused way to investigate an alternative to standard credit. Those are real benefits for the right user.
I would not recommend treating it as a universal bargain or as a replacement for budgeting. The 3.8 average rating suggests a mixed experience rather than effortless satisfaction, and the nature of leasing means the financial details matter far more than the convenience of the interface. The app can help you access an option; it cannot decide whether that option is wise for your household.
My final advice is simple: use it only after defining the need, setting a payment limit, and comparing the total cost with cash and conventional alternatives. If the numbers remain comfortable in a difficult month, the app may deliver meaningful value. If the purchase can wait, or if the complete commitment feels unclear, I would skip it and choose a slower, more transparent route.
My verdict: Acima Leasing is worth exploring for a specific, necessary purchase when ordinary credit is not suitable, but its free download should be viewed as free access to investigate—not as evidence that the underlying lease is inexpensive.
Frequently Asked Questions
01What is Acima Leasing, and how does it work?
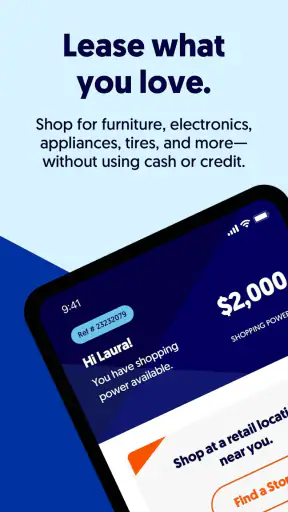
Acima Leasing is a lease-to-own service that may help shoppers obtain furniture, electronics, appliances, mattresses, tires, and other eligible products when traditional financing is not available. After applying and receiving approval, you choose an item from a participating retailer and make scheduled lease payments. The agreement is not the same as a conventional loan, so review the total cost, payment schedule, ownership terms, and early-purchase options carefully before accepting.
02Can I use the Acima Leasing app to apply for a lease?
The Acima Leasing mobile experience may provide account access, payment management, application-related information, and other customer services, although available features can vary by device, location, and account status. In many cases, you still need to shop through an approved Acima retail partner to select an eligible product. Before downloading, check the current app listing and official Acima website to confirm which functions are supported in your region.
03What are the eligibility requirements for Acima Leasing?
Approval requirements can depend on factors such as your identity, contact information, income, banking details, and other information requested during the application process. Acima is commonly marketed toward consumers who may not qualify for traditional credit, but approval is not guaranteed and terms can differ between applicants. You should provide accurate information, read all disclosures, and confirm the payment amount and total lease cost before completing the transaction.
04How much does an Acima lease cost in total?
The total amount you pay through Acima Leasing can be substantially higher than the cash price of the merchandise, particularly if you make payments for the full lease term. Costs may include an initial payment, recurring payments, taxes, fees, and other charges described in your agreement. Some customers may qualify for an early-purchase option that reduces the overall cost, but the exact savings and deadline depend on the contract.
05What should I know about payments, cancellation, and ownership?
You are responsible for making payments according to the schedule in your lease agreement, and missed or unsuccessful payments may lead to fees, account issues, or other consequences. Returning merchandise, canceling a lease, or purchasing the item early is governed by the specific agreement and applicable local rules. Read the cancellation, return, maintenance, and ownership sections carefully, and contact Acima customer support if you need clarification before signing.


